Detroit.png

By Ronald P. Bernardi

Stockton, California emerged from Chapter 9 on October 30, 2014 when U. S. Bankruptcy Judge Christopher M. Klein confirmed Stockton’s plan. Detroit, Michigan emerged from bankruptcy on November 7, 2014 when U.S. Bankruptcy Judge Steven Rhodes confirmed Detroit’s plan. Both judges ruled each plan as presented is fair and feasible to all parties involved. There are clear winners and losers as a result of these decisions. And much remains unresolved with many unanswered questions.

The facts of rough justice in Detroit and Stockton

As we wrote in our April 15, market commentary Detroit settles with UTGO creditors, there is a rough justice in bankruptcy. These two settlements confirm that sentiment. Here are a few facts surrounding the settlements.

Detroit settlement facts:

  • Detroit will pay companies insuring voter approved unlimited tax full faith and credit general obligation (UTGO) bonds 74% of the outstanding principal and interest. This settlement is significantly higher than Detroit’s initial offer of approximately 10%-12%. The insurance companies negotiated this settlement and have stated they will pay investors 100% of principal and interest payments.
  • Detroit will pay limited tax general obligation (LTGO) bondholders 34% of the outstanding principal and interest. This settlement is higher than the city’s initial 10%-12% proposal as well. The insurance companies insuring a portion of the LTGO debt have stated insured investors will receive 100% of promised payments. Detroit will exact a 66% haircut on investors of its uninsured LTGO bonds and the insurance companies.
  • Detroit’ s approved plan does not haircut water and sewer revenue bond debt.
  • Detroit will haircut all other NON-BOND debt investments approximately 88% – 90%, as it originally offered.
  • City pensioners’ benefits were impaired with maximum cuts of less than 5%; cost of living increases were eliminated or reduced depending on retiree class. Health benefits paid for by city were reduced significantly. Pre-bankruptcy, pension liabilities represented approximately seven times more than general obligation bond liabilities.
  • Detroit has paid approximately $135 million in bankruptcy fees.

Stockton settlement facts:

  • Stockton will pay investor Franklin Advisors a 12% recovery rate when a $4 million secured claim is included, according to Judge Klein. Franklin states its recovery rate is only 1% on its $33 million investment in Stockton’s bonds. Judge Klein approved the city’s proposed payout over Franklin’s objections. These lease rental revenue bonds were issued to make improvements to city parks and golf course.
  • Insurance companies and Stockton negotiated a settlement months ago on other debt with insurers taking significant haircuts. The insuring companies have stated investors in these issues will receive 100% of promised payments.
  • Judge Klein confirmed Stockton’s treatment of pension payments to CalPERS — pensions are not reduced either retroactively or prospectively. In an earlier ruling, Judge Klein stated Stockton was free to abrogate its contracts with CalPERS while in bankruptcy and that CalPERS is an unsecured creditor. He stated federal bankruptcy law preempts state law and therefore CalPERS’ lien claim as a legal basis to assess Stockton a $1.6 billion termination fee was invalid in bankruptcy. Stockton did not pursue a CalPERS haircut in its plan making these findings moot because Judge Klein did not go beyond Stockton’s request.
  • Stockton did exact some labor concessions including reducing employee salaries and the elimination of most retiree health benefits.
  • According to Stockton, it has spent approximately $13 million on bankruptcy-associated fees.

Let’s review some observations and takeaways.

No guarantees for bond investors

There are no guarantees for bond investors. Lending capital to municipal issuers entails a degree of risk. This is why thorough credit analysis of an issuer’s finances is critically important in assessing the risk of a municipal bond investment. One must examine an issuer’s underlying credit quality, deal purpose and deal structure in order to find the many quality municipal bond credits. However, a central question — “Are voter approved full faith and credit UTGO bonds secured?” — was never put before Judge Rhodes for consideration because companies insuring UTGO bonds settled with Detroit. Investors and market participants need clarity on this issue and it remains unanswered in the aftermath of the Detroit and Stockton Chapter 9 odysseys. This is disappointing to us. The absence of clarity on this question allowed Detroit to extract a cash windfall from this creditor class. This settlement is not a legal precedent since it was negotiated. The facts, however, are not lost on other stressed Michigan municipalities (and their attorneys). Detroit’s plan is now their practical precedent.

Our takeaway: Until this question is answered by a judge or addressed by the state legislature similar to Rhode Island’s legislation, we continue to warily view investing in many UTGO and LTGO Michigan bonds.

Pensions treated much more favorably than debt holders

Pension creditors’ interests are treated much more favorably than those of debt investors. In both cases, local leaders decided to push plans favoring retirees over all other creditors. In both cases, each judge decided not to intervene — they chose not to alter the proposed plans and spread losses more proportionally based on each creditor class’ relative exposure. Judge Rhodes stated Detroit’s “discrimination in favor of the pension claims in the plan is necessary to its mission” and “the discrimination is not unfair” and the plan “is a model”. He also noted that while his ruling found federal bankruptcy law trumps Michigan’s protection for pensions, Michigan’s voters approved a constitutional amendment to protect pensions and the vote is “entitled to substantial difference”. That is his justification for accepting the city’s plan of better treatment of pensioners compared to other creditors, including bond investors. Similarly, in the Stockton case, Judge Klein chose not to challenge Stockton’s plan that left pension payments unaltered even though he had ruled earlier these pension payments were NOT inviolable.

Our takeaway: Creditors should not expect a federal bankruptcy judge to overrule or amend a Chapter 9 plan haggled over for many months. Both plans discriminated between creditor classes and neither judge altered any terms. Settlements or the filed plan determined recoveries in both cases, not a judge’s decision. Most major creditors settled rather than litigating to the end. Creditors that did not settle saw each judge approve the plan presented by the filing city. In future cases, each creditor class should negotiate a settlement they feel is fair to their interests and, if one is not agreed to, they should litigate to the end. This approach will force the presiding federal bankruptcy judge to address important and unanswered questions. San Bernardino, CA is currently in Chapter 9 and has indicated, contrary to Stockton’s plan, that it is willing to explore possibly reducing payments to CalPERS. If it files a plan cutting pension payments, given Judge Klein’s ruling on this issue, it will be difficult for the judge to sidestep the question. The case will be interesting to watch.

Everything is negotiable in Chapter 9

Certain debt structures are more secure than others, so a waterfall recovery is somewhat applicable. This is why insurance companies were able to limit their haircut to 24% on Detroit’s UTGO bonds while Franklin Advisors is stuck with an approximate 90% haircut on Stockton’s lease revenue bonds. The former has a much sounder security structure than the latter so the companies insuring Detroit’s UTGO bonds had more leverage. Detroit understood this and quickly upped its initial 10% payout offer to 74% and happily pocketed the difference.

Our takeaway: Chapter 9 is very complicated. Solid deal structure is always important, especially in these distressed situations.

Bond insurance’s value is confirmed

At this point, the value of bond insurance is confirmed. The insurance companies have stated they will pay 100% of debt service payments to all insured debt investors. This is good news. These companies negotiated strenuously with Detroit and cut deals in their best interests. In the process, the interests of other parties were affected.

Our takeaway: In Chapter 9, insurers act as a unifying force and are motivated to maximize their recoveries. Many debt investors benefit from their negotiating strength. Insurance company interests are aligned with the interests of insured debt investors, but not necessarily all debt investors.

Key questions went unanswered in Detroit

Questions surrounding security of Detroit’s water and sewer revenue debt went unanswered. Non-tendering investors will not take any haircut. Detroit tried to foist changes on this group even though the city’s utility backs this debt and is not in bankruptcy. Detroit pulled back from its initial position due to lack of leverage (see above) and decided not to force the issue. It has been resolved for the time being.

Our takeaway: Detroit blinked because it realized its legal standing was shaky. Non-tendering debt holders were resolute in believing their investments were secured and chose not to agree to any impairment.

Significant pension liabilities remain

Stockton preserved pensions entirely and Detroit reduced its pension liabilities minimally. Liabilities will continue to represent significant portions of the respective operating budgets post-bankruptcy. For example, Stockton’s 2020 budget estimates pension payments will absorb 20% of the year’s expected revenues. How will they deal with this fiscal reality?

Our takeaway: Will post-bankrupt Detroit and Stockton be able to make these pension fund payments each year?

Pensions viewed superior to other creditors

Both submitted plans demonstrated local politicians view pensions as superior to all other creditors. It was an easier decision for them to subordinate the interests of bond investors to pensioners demonstrating municipal bankruptcy is an inherently political process. We believe state law and state politics greatly influences Chapter 9 dynamics and therefore, these factors are key to determining final outcomes in these situations. For example, it is not possible to file municipal bankruptcy in certain states, difficult to file in many others and relatively easy in yet another group of states. Some states’ law view bonded debt as a statutory lien, while others do not. Some state legislatures have passed laws that place elevated importance on honoring local municipal general obligation debt. These are important distinctions especially in the case of a financially distressed municipality. We believe, therefore, differing state laws and differing state dynamics will lead to varied outcomes of future distressed municipality situations across the country. We factor this view into our credit analysis process.

Our takeaway: Our federalist system promotes competition between states. This is one of the most dynamic and foremost features of our system of government. States are “laboratories of democracy”, wrote Chief Justice Louis D. Brandeis. Good ideas crowd out bad ideas and investment capital moves across state lines easily. It will be interesting to watch if the flow of investment capital is altered or adjusts in any meaningful way by the resolutions of these two bankruptcies. It will be interesting to see if certain “good ideas” become standard fare in future incidents of Chapter 9.

Please contact us if you have any questions. We thank you for your continued confidence.

Sincerely,
Ronald P. Bernardi
President and CEO
Bernardi Securities, Inc.
November 12, 2014

Sources:

  1. Bloomberg News
  2. Summary of Oral Opinion on the Record in Re City of Detroit Bankruptcy, Judge Steven Rhodes, November 7, 2014
  3. Oral Opinion of The Record in Re City of Detroit Bankruptcy, Judge Steven Rhodes, November 7,2014
 

BSI30YR.png

By Edward Bernardi

As we begin to celebrate our 30th anniversary, I have been asked to give you a review of our firm’s history, guiding principles and some of the changes I have seen in the municipal bond market. I have been in this business for over 55 years, and I have seen some dramatic changes during that time — from the use of ticker tape as a communication device to using today’s modern technology. I have seen municipal bond volume surge. Our client base has broadened. What hasn’t changed is our firm belief that we can outperform our competition — and earn the trust of our client — by concentrating our efforts, talents and expertise solely on the municipal bond market. Here are a few observations from an 84-year-old municipal bond professional.

Municipal bond specialists first and foremost

From the onset, our single interest was to run a sound investment firm specializing in municipal bonds. We wanted no part of the equity market and its volatility. While there is absolute importance in owning an equity or real estate portfolio, we wanted to specialize in an asset that allowed you to sleep well during the night. Our mission has been consistent for more than 30 years — specialize in the municipal bond market to deliver superior performance for clients. We are municipal bond specialists first and foremost, and will continue to be specialists solely in the municipal market.

Independent credit research

Our original business plan was to focus solely on the municipal bond industry by doing our own research. We wanted to develop in-house credit research, rather than depending on some outside source to tell us how a bond was rated, how good the bond was or was not. We wanted to have our own take. We wanted to make our own decisions as to the viability of a particular credit. The firm’s ongoing investment in our research efforts provides us with added confidence in the credits we place with clients and offers opportunities to find solid credits at good prices for our clients. This approach continues to this day.

50 years ago we received news and offerings via snail mail and ticker tape. Today, the information is delivered in fractions of a second. I guess progress is progress, but I’d rather take my time and do my homework rather than being rushed into the decision making process. Again, a good research department allows us to make those quick decisions without the inherent risks of decisions without thought.

Better regulation & investor protection

In the early days of my career the municipal market was free of “government interference.” As a result, a number of rogue firms took advantage and hurt communities and investors. Today, the market is regulated by a number of federal and industry-funded agencies, which have brought the interests of the municipal bond market more in line with the clients it serves.

Municipal bond tax exemption repeal threats

The question of municipalities retaining their right to issue debt whose interest payments are tax-free from federal income taxes comes up again and again over time. About 30 years ago, certain politicians attempted to do away with the exemption. Governors, mayors and school superintendents throughout the country vigorously objected. The matter was dropped.

Today the question is being raised again and it is a bad idea. Repealing or capping tax-exemption will make it more expensive for communities to borrow. Communities will still need to invest in their infrastructure.  They will issue taxable bonds instead forcing local taxes and fees to increase.

More than a half-century of changes — and gratitude

Yes, it has been quite a run. My life has been devoted to this industry for more than a half-century — the last 30 years to Bernardi Securities. It is impossible for me to adequately describe the sense of profound joy and pride I feel for the Bernardi team on this, our 30th anniversary. Nor is it possible for me to sufficiently thank our clientele — from those who allowed us to serve their investment needs in the early years to the younger generations who have helped to drive our growth.

A special thanks to the municipal bond specialists of Bernardi Securities. Their honesty, care, dedication and service to our clients built the foundation of our success.  Each and every one of our specialists is a credit to the firm.

Lastly, with great pride I salute my son, Ron Bernardi, who met the new challenges of this day and age — and built a firm which is now one of the most respected in the industry.

The success of the firm will forever represent the singular reward of my business life.

I thank you all.

Sincerely,
Edward Bernardi
Chairman
Bernardi Securities, Inc.
November 5, 2014

Premium-Municipal-Bonds.png

By Matthew P. Bernardi

Many investors find it difficult to pay a price greater than par for a bond. We often find this hesitation is purely psychological and causes some investors to miss an advantageous structure in a low interest rate environment. This market commentary is written to explain why premium municipal bonds often offer value in today’s market — helping to justify paying above par for a bond.

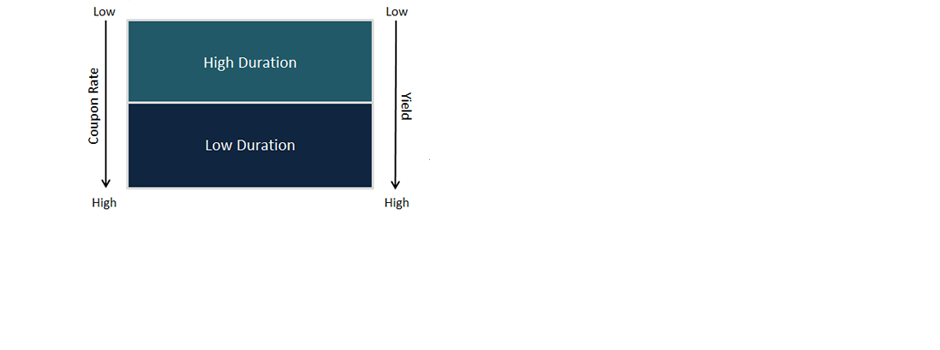
Premium bonds carry a coupon rate that is higher than current market yields. This causes the price of the bond to trade above the par value ($100) to bring the overall return in line with current rates. The higher coupon of premium bonds creates a number of benefits for the investor.

Reinvestment at higher rates

If rates rise, the higher coupon payment (i.e. cash flow) of premium bonds can be reinvested at the high rates. Take for example two $1,000,000 par amount portfolios. One is invested in premium bonds carrying 5% coupons, the other in par/discount bonds with 3% coupons. The first portfolio generates cash flow of $50,000 per year compared to the second at $30,000 per year. An additional $20,000 in cash flow from the premium bond portfolio is now available to take advantage of rising rates. $50,000 compounded at a 4% yield for 10 years amounts to $74,012 — whereas $30,000 amounts to only $44,407.

Less volatility

Higher coupon bonds are inherently less volatile than lower coupon bonds. Duration is a measure of the sensitivity of the price of a bond to changes in interest rates. The higher the duration, the more volatile a bond’s price changes as rates fluctuate. There are a number of factors affecting the duration calculation. One is a bond’s coupon rate. Because a relatively higher coupon returns cash flow to the bondholder sooner, it is a favorable input in the calculation and lowers the duration (volatility) of the bond.

Dearth of demand

There is a large contingent of the retail investor base that entirely avoids premium bonds. This reduces demand and makes them less expensive for others to buy at relatively higher yields. If you have read this far, hopefully you are no longer part of that crowd.

A defensive opportunity — with one caveat

The benefits of premium municipal bonds described above provide investors with both an opportunity and a defense mechanism in a rising rate environment. One caveat, however, should be noted about premium bonds — often these types of securities carry a short-term call date. Because of the high coupon, the likelihood of a call is often relatively high. Investors must take into account this possibility in the context of the overall portfolio structure — and should be properly compensated in yield return priced to that date.

Please contact us if you have any questions on portfolio strategies for a rising rate environment or would like a portfolio review.

Sincerely,

Matthew Bernardi
Bernardi Securities, Inc.
October 2, 2014


2014-Mid-Year_2.png

Since June of last year the economy has added almost 2.5 million jobs and the unemployment rate has fallen from 7.50% to 6.08%. Nonfarm payrolls have surpassed pre-crisis levels and PCE inflation readings — although subdued — have increased from 1.16% to 1.48%[1].  Many economists maintain a positive employment outlook as well, calling for the unemployment rate to fall to 5.8% in Q1 of 2015 and inflation to touch the Federal Reserve’s target of 2% in that same quarter.

What’s keeping bond yields so low?

With a healthy backdrop and positive outlook it is difficult to accept why the 10-year Treasury bond trades at a lower yield today (2.46%) than it did a year ago (2.60%). The 30-year bond has had an even larger move, going from 3.67% on July 29th, 2013 to 3.22% today. Municipal yields have moved lower too — and to an even greater extent. The effect of higher tax rates setting in, reduced supply and continuing improvement in municipal balance sheets are factors responsible for the relative move of lower municipal bond yields.

There are a number of explanations why market pundits calling for a rate shock have been disappointed. For one, investors have reduced their projections of the Federal Reserve’s “normalized”[2] federal funds rate level. Secondly, global central banks — led by the European Union, China and Japan — continue to ease as they try to keep their currency values relatively weak. A closer look at the yield curve, however, may give us the most appropriate answer for why we have experienced this fall in long-term rates. While the 10- and 30-year bond yields have dropped, shorter term rates have actually been on the rise.

Higher rates means lower rates

The emerging theme of a flattening yield curve, which we overviewed in our March market update, has largely played out as expected. Since the start of the year, the difference in the 5-year and 10-year Treasury bonds has fallen from 1.28% to 0.77%. The 2-year/10-year spread has moved from 2.64% to a 1.94% difference. This move is in response to the market projecting slower growth in the future brought on by higher short-term rates prompted by the Fed’s eventual tightening. Should rate increases arrive sooner or greater than projected (3Q 2015), the yield curve flattening will become more pronounced, if not inverted. (i.e. higher short-term rates compared to longer-term rates.)

Municipals offer compelling opportunities

From a relative rate perspective, municipals offer compelling after-tax risk-adjusted returns, with the 10-year AAA rated tax-exempt benchmark municipal trading at 89% of the 10-year Treasury yield.[3] This ratio averaged 86% in the 7 years prior to the crisis. Even at the 15% Federal tax-bracket, the taxable equivalent yield is above Treasuries. The elevated level of tax-exempt rates compared to taxable Treasuries is largely due to perceived credit weakness in the market as the headlines of Puerto Rico and Detroit linger. Our own backyard — the State of Illinois — also contributes to market stress. For a “bottoms-up” research firm like ourselves, this creates opportunity. We touched on this in our Illinois Effect white paper published last month.

Credit research lessons in Detroit distress

These pockets of distress have created opportunities and lessons alike. Detroit’s bankruptcy filing, to date, has failed to provide any legal clarity regarding the putative secured status of Unlimited Tax General Obligation bonds and Limited Tax General Obligations. Instructively, the City’s public position and certain proposed and agreed upon settlements with bond creditors have provided clarity as to how Detroit’s officials view the security of these debts. We are interested to see if the bankruptcy court finds these agreements and proposals fair and equitable with respect to each class of claims that is impaired. This opinion will provide a degree of legal clarity and it will be very instructive to us as it relates to Michigan bonded debt, generally.

Detroit’s final settlements with bondholders may portend what other investors might expect as settlement in future distress situations occurring elsewhere in Michigan. We do not necessarily infer similar treatment for non-Michigan general obligation bonds during distress scenarios, but clearly a bad precedent seems to be developing in Motor City. The market will always be regional in price, politics and legal structure. Adhering to our Three Pillars of Credit Research has allowed us to successfully navigate away from such municipal credit strains and the politics of a bankruptcy settlement.

Continued economic improvement likely ahead

As the year progresses we expect the economy will continue to improve. The health of the credits we follow should improve simultaneously as property values rise, tax revenues increase and pension funding recovers.

As always, please call us if you have any questions or would like a portfolio review.

Sincerely,
Matthew Bernardi
Bernardi Securities, Inc.
July 29, 2014

[1] Source: Bloomberg. The preferred measure by the Federal Reserve of inflation is the change in the Personal consumption expenditures price index (PCE).
[2] When the fed funds rate is consistent with real GDP equaling its potential level (potential GDP).
[3] Source: Bloomberg. Ticker: MUNSMT10 Index Index


Good afternoon, I am pleased to be here today with you, Kevin and Mayor Benjamin and have a conversation about the importance of municipal bonds to your constituents. Your have heard from Mayor Benjamin how important municipal bonds are to the citizens of Columbia; Kevin has explained how critical tax- free municipal bond financing is to building our airports. My role here is to complement these 2 gentlemen, explain our firm’s role in the marketplace and give you a history of the municipal bond market, share a few of my experiences.  I read in the invite I am a “seasoned expert”……which means I am long in the tooth so I think I bring a historical perspective that hopefully will help you.

So first, let me give you a little background information about our firm. Bernardi Securities is a Chicago based municipal bond specialty firm, established in 1984. We are regulated by the SEC, FINRA, state agencies, Municipal Securities Rulemaking Board(MSRB). We are a municipal bond market maker and rely on our in house credit research team. We  publish and speak on current issues like: threat to tax-exemption, market transparency and disclosure I began my career, 1980; Our Chairman, Edward Bernardi began career in the late 1950’s. What we do is important to the clients we serve. They count on the municipal bond market and they count on us to help them navigate through it.

I am here today because I believe what we have to say is very important to you and your constituents. This is not so much about Ron Bernardi’s interest as it is about the interests of the people living in Columbia, South Carolina, the people I serve, the people living  in your congressional districts. When you leave today, I hope you will remember this: Municipal bonds build America.

The municipal bond market is very important to this country. Generally, it functions well, day in day out, year after year and has been doing so for over 100 years. It is far more efficient, more transparent than when I began in 1980, improving every year. It is far from perfect, but it is a sound , good, fair marketplace. And,  it needs to continue to evolve, progress in sensible, measured ways. Congress’ mission should be  to help the municipal bond market evolve and improve,  not curtail or hinder it. Repeal tax-exemption, curtail it any meaningful way and it will be harmed. And your constituents will bear the brunt of the effects. Not Bernardi Securities, not Mayor Benjamin and not the airport council ….your constituents.

So what is Bernardi Securities role in the market? We have three primary functions: First, we assist issuers in planning capital projects and raising funds for infrastructure projects. Ithaca , NY in August of 2013 refinanced approximately $ 3 million loan;  it lowered its annual payments, freeing up funds to be used for other community investments.  Bernardi underwrote that transaction. Rothschild, Wisconsin recently updated its water/sewer plant;  we  raised  several million dollars it needs for that community investment. These are two  examples of communities needing  access to low cost capital to make improvements. The present day municipal bond market allows them to do this.

Second, we assist community banks and individual investors invest capital; we help them manage their bond portfolios relying on our credit research as the foundation.

Lastly, we are a market maker, trading bonds after the  issue has come to market. Markets need liquidity; investors want assurance they can sell their bonds at a reasonable price and timing before maturity- we help provide this liquidity. Our clients are conservative, they regard asset class as their mattress money. Generally, investors appreciate the security municipal bonds offer and many like to invest in local projects.

There are  two key points to make here:

  1. Municipal  market encourages investors to invest conservatively and that is good for all of us.
  2. In our experience, local investment tends to be an excellent governor of behavior; projects tend to be more sensible.

The notion that tax-exemption fosters profligate projects is wrong; sure,  there are situations, but almost universally in my experience over 30 years, communities borrow what they can afford to pay back and tax-exemption allows them to borrow at a lower rate. These are healthy results the market helps to produce.

I want to briefly touch upon the history of the municipal market. And the important role it  has played in the national and local economy. Again, I say to you,  municipal bonds have built America.

A 2013 engineering society study calls for $3.6 trillion in infrastructure  investments  by 2020. Our infrastructure is aging, needs updating.  The municipal  market should continue to have the primary role in making these investments and any contemplated federal policy changes should not result in harming the market. We need  PUBLIC PURPOSE INFRASTRUCURE PROJECTS (roads, schools, water/sewer plants, county courthouse, airports, village halls, public libraries….) After all, 75% of country’s infrastructure is financed with municipal bonds.  Large and small projects are possible and the present day, tax- free market structure is well suited to raise capital for the fragmented needs of the market.

Additionally, bond issuance creates meaningful, productive jobs paying a salary above minimum wage.

Importantly, municipal bond investors comprise a diverse cross section our population, saving for their retirements. It is incorrect to think the municipal bond market benefits only or primarily the wealthy.  The premise is false. I will have more to say on this issue later.

Lastly, U.S. public finance market is envied around the world. The Chinese national government has begun a trial program to develop a transparent, locally controlled  municipal bond market in order to clean up its current, central government controlled system. India has explored developing  a municipal bond market. Certain European governments,   where public finance  historically is controlled by central governments,  are adapting dynamics like our model. I have studied public  finance systems around the world  and none I know of come close to ours when measuring a system’s  economic efficiency, project execution time efficiency, local  control in decision making. Our  system is the “cat’s meow”  of the all the world’s public finance systems!

Turning it upside down, substantively altering it would be a serious misstep.

The history of the municipal bond market runs parallel to this nation’s history in many respects. Tax-exemption was created  in 1913 – helps ensure  “reciprocal immunity” ; the municipal bond market’s  roots go back much further. We have all heard the famous quote: “ power to tax involves  the power to destroy”. These are the words of Chief Justice John Marshall in  McColloch versus Maryland, 1819. The decision limits the ability of a state to intrude on sovereignty of federal government and  vice versa.

In 1894, the Supreme Court ruled in Pollack vs. Farmers Loan Trust that federal income taxes on interest were unconstitutional. Additionally, the decision established the notion of “inter-governmental immunity” which protects state and local governments borrowing abilities from federal government interference. The Pollack decision  is  the reason why when the  16th amendment (federal income tax) was enacted, federal taxation of municipal bond income was prohibited.

This prohibition was written into the law because Congress realized if the  federal government could arbitrarily tax municipal bond  income, then state and local governments would not enjoy freedom from possible federal government overreach. Let’s turn this around: imagine the outcry here in Washington if a state government began taxing income earned on u.s treasury bonds.

RECIPROCAL  IMMUNITY PROVISION, R.I. P. as I like to call it, prevents this from occurring. R.I.P. is fundamental to the federalist system our nation is built around. For this reason, unlike any other deduction, the exclusion of municipal  bond income was codified into law in the Revenue Act of 1913.

Tax-exemption is unique from all  other tax expenditures. Tax-exemption is Not some tax loophole inserted into the tax code in the middle of the night. It is rooted in the federalist system, it is time tested, it has survived multiple recessions, two world wars, the Great Depression and the Great Recession.

So how does the market operate,  why it is attractive for issuers, investors, the general population? First of all, it is a localized market. It is fragmented and this feature is intrinsic to its nature; as long as R.I.P. exists, the market will  remain fragmented. It is attractive for issuers because it’s  relatively deep and liquid market and tax-exempt status allows more affordable funding. Solid quality issuers today borrow at approximately 2.50% (“ aa”, index as of 6/23/14)  for 10 year loan, 3.50% for 30 years.

These low borrowing rates makes financing the new school, the village hall expansion, road improvement project fixing all those winter potholes in your town more affordable. If the market worked poorly, would borrowing rates be this low?

The present day market helps ensure localized control. Inherent in our system,  is this crucial dynamic ……to me, this is the most important feature of our public finance system. There are approximately 50,000 distinct issuers of municipal bonds – look at your local tax bill, most of the line item issuers , issue bonds. The market gives those issuers access to capital , allows them to structure their borrowings the best way to suit their needs.

Your constituents decide IF a school is built, its scope, how to pay for it.

Your constituents decide if the county courthouse should be expanded, how many years to take to pay off loan.

Your constituents decide if the public library, public parks should be built, the  location.

This is a healthy dynamic, and a  very good governor of cost and efficiency.

The market is attractive for investors: Over 70% of outstanding municipal bonds are held by individual investor.

They like to invest in the market for these reasons:

  1. Preservation of principal & low default rates
  2. Over the long term,  it is uncorrelated to economic swings
  3. It offers the opportunity to invest directly in the local community
  4. It offers countless options for investors
  5. And Tax-exempt income is an over-arching reason asset class is attractive

Repeal tax-exemption, cap the exemption at 28% as some proposals call for and  your constituents will see higher taxes, higher fees, fewer capital improvements in their communities, scaled back  projects. If you believe in the principles of federalism embodied in the constitution.  If  you believe state and local governments should have wide latitude to independently finance public purpose infrastructure projects that your citizens need, want and are willing to pay for. Then ladies and gentlemen, radical changes to the present day muni market should not occur.

It is really that simple.

Having said that, our market needs improvement and there are steps that can easily be taken to make improvements. A modified BAB Program would be helpful as a complement, not a replacement to current market. A lot of talk about the success of BAB program. There were many and overall the program was good as it stabilized the market.

But the BAB program had some serious shortcomings, inefficiencies of its own.

The Tax-Credit Option is a non-starter, in my view. The market is thin, highly illiquid, non- transparent. There is minimal investor interest in tax credit market structure.  Tax-credit was offered as a BAB option and it was near universally ignored. Issuers and investors chose not to use it.

So how do we make our market better for Mayor Benjamin and residents of Columbia, SC and  your constituents? Most importantly, the market needs clarity; uncertainty brings higher cost.  And oftentimes, clarity requires singularity.  The  municipal  market needs clarity NOW!

By that I mean tax exemption for public purpose issuance is untouchable. That should be the resounding message. And then clearly define “public purpose”. That should be the topic of debate. Perhaps, it should be narrowed. In my view certain issuance currently tax-free, should be prohibited thereby returning tax money to the treasury.

Secondly, stop talking about and  advancing proposals focused on  partial or prospective repeal; no 28% cap .  This adds to the air of uncertainty and increases borrowing costs for your constituents. Thirdly, increase the Bank –Qualified  limit from its current $10 million cap.  Doing so will increase bank investing in infrastructure projects and should  lower borrowing costs.

Lastly, issuer  disclosure must continue to improve.  It is much better today than what existed a handful of years ago, but there is work to do in this area. I see we have about 20 minutes remaining for your questions so I will end with this, repeating how I began my remarks:

Muni bonds build America. The municipal bond market is very important to this country. We need Congress’ help to build upon, improve what we have here.

Thank you.

July 2, 2014


$5.225 Million Electric System Revenue Refunding Bonds, Series 2014

The Bonds are being issued for the purpose of refunding, on a current basis, the 2014 through 2030 maturities of the City’s Series 2010A Taxable Electric System Revenue Bonds (Build America Bonds-Direct Pay).  The City joins a number of other Wisconsin municipalities taking advantage of extraordinary redemption provisions to refund their direct-pay Build America Bonds (BABs).  The BAB program originally offered a federal interest rate subsidy of 35%; however, those subsidy payments were reduced during last year’s federal sequestration budget cuts.  A lesser reduction of 7.2% has been implemented for fiscal 2014.  With sequestration cuts in place and a relatively low interest rate environment, the city could realize considerable savings refunding the BABs with tax-exempt debt.

The Series 2014 Bonds are payable only from and secured by a pledge of Net Revenues derived from the operation of the City’s Electric System. Furthermore, the City covenants to maintain Net Revenues sufficient to cover annual debt service at least 1.25x and show at least 1.25x coverage on any existing and proposed bond issues.  The Bonds are also secured by a debt service reserve account, which shall be funded at the lesser of: (a) 10% of the proceeds of the Bonds, (b) maximum annual debt service on the Bonds in any future Bond Year; and (c) 125% of average annual debt service on the Bonds.   Total revenue bond debt service coverage after tax equivalent transfers was 1.40x in fiscal year 2013. The Bonds are non-rated.

The City of Black River Falls, with a 2010 U.S. Census population of 3,618 and a current estimated population of 3,600, comprises an area of 1,699 acres and is located approximately 130 miles southeast of the Minneapolis-St. Paul metropolitan area.


Bond-Right-Side-Up2.png

By Ronald P. Bernardi

Detroit Settles on UTGO Debt

The family vacation photo that made its debut this past December, “Will Detroit turn BOND upside down?”, returns today, right side up.

Last week Detroit reached a settlement with three bond insurers over the treatment of its unlimited tax general obligation bonds (UTGO) agreeing to pay this group of creditors 74 cents on the dollar of the $388 million owed.  The remaining 26% surrendered by UTGO bond creditors will be assigned to support various pension plans for city employees.  Outstanding insurance policies on the UTGO bonds remain in effect ensuring full payment of debt service to investors as originally scheduled.  The city’s bankruptcy plan prior to this settlement offered as little as 15 cents on the dollar to the UTGO creditor group.  It  will be amended to reflect this settlement and is subject to approval by U.S. Bankruptcy Judge Steven Rhodes.

 BOND, Right Side up?

According to the final official statement issued and approved by City of Detroit, Michigan Series 2005-B bond issue, “The Bonds are full faith and credit unlimited tax general obligations of the City duly authorized by the City’s voters and secured by a pledge of the full faith and credit of the City. The City is authorized and required to by law to levy and collect ad valorem taxes without limitation as to rate or amount upon all taxable property in the City to pay the principal of and interest on the Bonds when due.”

Despite the obvious clarity of the text, City of Detroit emergency manager Kevyn Orr, until last week, claimed the Series 2005-B UTGO bond issue (and other similarly structured issues, as well) was “unsecured” — he viewed it’s security no different than the unpaid coffee vendor’s bill. As we wrote last December, there is a great deal riding on Detroit’s workout plan and the need for it to treat UTGO and LTGO bondholders equitably and differently than other creditors.

In our December market update, we suggested the city implement a distribution “waterfall structure” and establish a hierarchy delineating the order and percentage priority in which funds are to be distributed to various classes of debt holders. Such an approach helps ensure that different types of creditors receive the priority of payment they deserve.

Last week’s agreement, if approved by Judge Rhodes, is a significant positive step for Detroit and moves the city in the direction we suggested months ago. We are heartened by Mr. Orr’s about face and believe it is exceptionally important to Detroit’s future. His motivations for changing his position are unknown to us and we give him great credit for doing so. Below, we offer our conjecture as to why he agreed to quintuple his offer to UTGO creditors:

  • Original offer was untenable.  Orr recognized the city’s offering of 15-20 cents on the dollar to voter approved UTGO bond investors with a dedicated millage backing was untenable in Judge Rhode’s court — words like “duly authorized” and “full faith and credit” matter to the Court, we believe.
  • Increased negotiating leverage with other creditors. The agreement removes an important creditor group from the negotiating table, increasing pressure on other, larger creditors to settle. Judge Rhodes has consistently warned creditors to settle with the city. Recently he told creditors, “The message is now is the time to negotiate.” There’s a rough justice in bankruptcy and Judge Rhodes strikes us as someone willing to mete out a solution as he sees fit and move on. The remaining creditors may want to return to the negotiating table to cut a deal.
  • Better potential to market future municipal bonds. The workout crafted with bond insurers means bondholders will be paid in full; prospectively, this should help Detroit sell future debt issues to investors.

We are hopeful Mr. Orr reaches a similarly equitable agreement with LTGO creditors quickly. Settlement with this creditor group is important for Detroit. Any potential settlement will be less than the 74 cents on the dollar agreed to with UTGO creditors consistent with a “waterfall structure” solution. But, in our view, it should be substantially greater than the 15-20 cents payout as cited in the city’s filed plan. This creditor group — and others too — have millage dedicated to their security interest and should be treated differently, better than creditors lacking this claim on millage. The city can justify to the Court paying a higher rate of recovery to this group. An equitable agreement with this creditor group will strengthen Detroit’s access to capital markets in the future. Importantly, it will also help lift the undeserving pall currently hovering over much of the LTGO debt issued by municipalities across Michigan.

Still “Waiting for Godot” in BOND

Samuel Beckett’s 1953 tragicomedy depicts the story of two homeless men, Vladimir and Estragon, who wait endlessly for someone named Godot. They are unsure who he is and what he will bring them. They are hopeful when they meet him he will have a solution to their plight. Godot never arrives.

Our metaphorical BOND has endured its own frustrating version of “Waiting for Godot” in recent years, too. Bankruptcy filings in Stockton, San Bernardino and now Detroit have failed to answer a significant question overhanging the market — Are voter approved, unlimited tax general obligation bonds “secured”?

Mr. Orr claimed otherwise, until last week. Bond investors, insurers and other market participants strongly disagreed with him. The settlement means Mr. Orr has changed his mind and now agrees with this group. This is a fine development for Detroit — and other Michigan bond issuers and investors —  in part, because it helps to debunk the notion voter approved general obligation bonds are “unsecured”.

But the agreement between Detroit and UTGO creditors, if approved, obviates the need for Judge Rhodes of having to answer the key question. For many investors holding UTGO and LTGO bonds issued by Michigan municipalities, this is a disappointing and frustrating outcome of last week’s agreement. Clarity requires singularity oftentimes and this question is one such case. Similar to what Vladimir and Estragon feel as they wait in vain for Godot, many investors wish the question would be answered in a court of law.

Until this question is definitively answered in a courtroom or by state legislatures, certain issuers will continue to use the lack of clarity as leverage. They will dance around the concepts of “willingness” and “ability” to pay debt service on their bonds forcing investors to litigate to protect their interests. This dynamic creates market uncertainty and investor unease. Both are bad for the market, issuers and investors.

The question at hand needs to be answered by a thoughtful court. It appears Judge Rhodes will not be presented with the opportunity to answer it. And it appears Godot will not be arriving anytime soon to answer the question either.

Ronald P. Bernardi
President and CEO
April 15, 2014

Fishing3.png

By Jeffrey D. Irish

Following Janet Yellen’s recent testimony, many investors may just want to wait for Federal Reserve policy makers to raise interest rates before committing money to the bond market. After all, the fed funds rate has been held in the 0% to 0.25% range for years so rates must go up, right? The answer is perhaps, but interest rate timers may have wasted four years waiting to catch a bigger fish – and just missed it. Most of the hike in interest rates that investors have been waiting for may have already happened.

In just the past 15 months, the yield on the benchmark, 10-year Treasury note has climbed from 1.65% to 2.71% where it stands as of this writing. That’s a 106 basis point increase in yield at the same time the fed funds rate has remained unchanged.


Analysis of past four Fed tightening cycles

Shown below is an analysis of the past four Fed credit tightening cycles along with the resultant yield for the 10-year Treasury note during the same period. You will notice that the fed funds rate actually ended up higher than the yield on the Treasury in three of the four cycles.

July 1, 2004 thru September 2007

  • Fed funds rate increased from 1.00% to 5.25% – plus 425 basis points
  • 10-year Treasury note yield decreased from 4.56% to 4.52% – lower by 4 basis points

February 30, 1999 thru May 16, 2000

  • Fed funds rate increased from 4.75% to 6.50% – plus 175 basis points:
  • 10-year Treasury note yield increased from 5.28% to 6.27% – plus 99 basis points

February 4, 1993 thru February 1, 1995

  • Fed funds rate increased from 3% to 6% – plus 300 basis points:
  • 10-year Treasury note yield increased from 6.41% to 7.49% – plus 108 basis points

January 1988 thru February 1989*

  • Fed funds rate increased from 6.50% to 9.75% – plus 325 basis points:
  • 10-year Treasury note yield increased from 8.79% to 8.98% – plus 19 basis points

*Fed funds rate figures for this period are approximated as Federal Reserve decisions were not officially announced at the time.

It is important to remember that the Fed – aside from the quantitative easing policies, which are now being tapered – is not usually buying or selling longer dated bonds. Traders, investors and other market participants will generally dictate the yields on long bonds. Pricing is based in large part on future inflation and growth expectations. As the economy has shown signs of recovery, these participants have been driving the yields of long bonds upward to compensate for the expected erosion of net return that is caused by inflation.

When the Fed does start to raise the fed funds rate, a perverse thing, as far as those on the sidelines are concerned, usually happens as evidenced by the preceding analysis – the rates on long-term bonds peak and then start to fall. This happens because the prime rate is tied to the fed funds rate, which is directly tied to almost all forms of consumer and most business borrowing. When these rates go up the cost of borrowing goes up, which slows the economy. A slowing economy is usually welcome news for bond investors because costs of goods and services tend to stabilize or even fall, which preserves the buying power of fixed income investments.

The rising-rate advantage of individual bonds

The reason many typical, buy and hold, municipal bond investors may not be buying longer-term bonds right now is because they have been scared into thinking that the value of their investment will decline sharply if interest rates rise. It is the dreaded total return argument.

For those buying individual bonds, perhaps the most important thing to consider is that you know the score of the game at the outset. Unlike bond fund investors ¬– whose investment lacks a maturity date and therefore will lose principal if rates rise – the individual bond buyer will receive their money back at maturity. From the first inning, the investor buying individual bonds knows the final score: the yield and the maturity. Fund investors lack that certainty – their return will fluctuate.

Calculating the cost of waiting

Here is an illustration to bring this all home. Assume one has $100,000 available to invest. Let’s say you can put the money in a long-term bond with a 4.00% coupon, priced at par or park it in a one-year bond yielding 0.50%. After a year, the investor in the ultra-short bond has received $500 while the long-term buyer earned $4,000. The short-term investor retains their options but at a steep cost.

Let’s say the ultra-short investor guessed correctly, though, and after one-year he or she is able to invest in a bond yielding 5.00%. The 5.00% bond generates $1,000 more interest annually than the 4.00% bond but it will take about four years for the short-term investor just to break even with the investor who put his money into the 4.00% bond today.

If the investor is right about the direction of rates but wrong about the size of the move – for instance, one is only able to invest at 4.75% – it will take about five years for him to catch up. If rates remain where they are, or decline, the investor will never catch up.

We are not advocating abandoning your current investment parameters to buy 30-year bonds. Rather, stick to your existing ladder and forget about trying to time the market. There’s a hefty price to pay for thinking you can predict the unpredictable.

As always, please contact us if you have any questions, or would like us to review your portfolio with you.

Jeffrey D. Irish
Vice President
March 28th 2014


Weiji2.png

The municipal bond market’s behavior in 2013 could be summed up by the old saying that the Chinese word for “crisis” – wēijī – is actually composed of two characters representing “danger” and “opportunity.” John F. Kennedy is credited for popularizing this concept in a 1959 speech, and it has since become a staple of motivational speakers looking to inspire their audiences to seize the opportunities that appear in the midst of uncertain times.

This is a great saying, but a little research shows that this is another one of those stories that is a little too good to be true. Wēi does roughly translate to danger, but the Chinese character jī actually is closer in meaning to “crucial/critical point” than opportunity.

In that context, however, wēijī could be an even more appropriate term to use when considering the year 2013:

  • Yields shot up. The 10-year U.S. Treasury moved from a low yield of 1.63% in May to finish the year at 3.02%.
  • Index returns soured. Municipal bond indexes recorded their worst performance since 1994.
  • Great Rotation speculation escalated. Municipal bond mutual funds ended the year with a nearly eight month-long streak of weekly withdrawals. This supplemented the speculation of a “Great Rotation” from bonds into the stock market.
  • Detroit doom looms. Detroit’s Chapter 9 bankruptcy filing has opened up legal questions that could have significant effects on the entire municipal debt marketplace.

Historians indeed may look back on 2013 as having been a crucial point for municipal debt investors. On the other hand, we at Bernardi Securities see it as a time when the fundamentals of our investment process and philosophy – separate account, professionally managed portfolios utilizing rigorous credit analysis and a disciplined adherence to a laddering strategy – have become ever more important to our clients.

In short, we think that this possible crucial point offers real opportunity to the committed municipal bond investor.

Interest rates – Are they finally moving (and staying) up?

Ever since the Federal Reserve embarked on its unprecedented quantitative easing program to force interest rates down to record-low levels, fixed income investors have been awaiting the inevitable return to more normalized levels. 2013 could possibly have been the turning point, as the U.S. economy has finally exhibited signs of breaking out from tepid – though sustained – growth.

We have also seen the Fed make its first tentative steps to ease its flood of liquidity into the market, via its decision in late December to begin tapering its purchases of longer-term Treasuries and mortgage-backed securities.

The yield curve has responded accordingly, as investors anticipate higher rates sooner. This is demonstrated by the steepening of the yield curve, with the tax-exempt municipal curve graphed below. Short term rates are still anchored by the Fed, though longer-term rates have risen as the market anticipates higher growth and inflation – hence, higher yields – in the future.


Source Bloomberg

The obvious question is whether this is the start of a sustained rise in interest rates. Our answer is – we don’t know and we will not speculate. We do not make aggressive interest rates bets, and we certainly have seen a number of very smart analysts prematurely call an end to this low rate environment.

Furthermore, we have seen a number of 50 to 60 basis point increases in rates since the 2008 financial crisis, only to see subsequent rallies in the bond market. Indeed, an unexpectedly weak employment report this month has led to the 10-year Treasury moving back towards 2.75%, which is roughly where it was back in August.

This reminds us once again of one of the strengths of the laddered bond portfolio for the committed municipal bond investor – it takes fear (or overconfidence, for that matter) out of the equation, and replaces it with a disciplined approach to investing. You may recall the December 11th perspective and strategy discussion written by one of our vice presidents, Jeff Irish. Jeff discussed the cost of waiting for rates to rise while money stagnates in near zero-percent money market or ultra short-term bond funds. Investors waiting on the sidelines for an increase in market yields are losing more and more of the “time value” of their money. In the meantime, the owner of a laddered municipal bond portfolio has been receiving a stream of income.

It pays to remember that we are now approaching the sixth year of a zero interest rate environment. We don’t know if any of us could have foreseen this back in September 2008 when Lehman Brothers filed for Chapter 11 bankruptcy. It is also worth noting that Federal Reserve officials have made it clear that while the Fed is beginning to taper longer-term bond purchases, they expect short-term rates to stay near zero for at least a couple of more years.

In light of recent history and continued uncertainty, we maintain that a commitment to the bond ladder gives the investor the best means for seeking income.

The stampede from bond funds and ETFs

As you well know, one of the fundamental rules of fixed income investing is that the prices of existing bonds decline as rates increase. 2013’s decline in bond prices translated into higher yields in the intermediate and longer-term markets. Tax-exempt municipal bonds were affected along with taxable securities, as reflected in the 2.6% loss recorded by the benchmark Barclays Aggregate Municipal Bond index.

The average general and insured municipal bond fund lost 4.1% in 2013, while the iShares National AMT-Free Muni Bond exchange traded fund (MUB) lost 3.44%. Such figures spurred withdrawals from municipal bond mutual funds and sales of muni ETFs in 2013, which forced such funds to sell bonds into a declining market in order to raise cash for redemptions. This in turn led to further weakness in the market and a divergence of fund and ETF prices from net asset value (NAV).

On the other hand, almost all of our separately managed, laddered portfolios did better than the Barclays index, and avoided most of the volatility seen in the mutual fund and ETF marketplaces. As noted in our August 28th piece entitled Outperforming the Madness of Municipal Bond Fund Herds, the separately managed bond account allows for greater control at times such as these. It allows the investor to avoid being swept up in rush of the crowd to the exits; instead, he or she has the ability to select or remove specific bonds from their portfolio, and the timing of such actions. This is particularly helpful when harvesting losses to shield other investment income and capital gains.

The holder of a laddered account actually finds a silver lining in rising rates, in that maturing securities now can be reinvested at higher yields, while soon-to-mature securities can be swapped into higher-yielding longer-term issues. This is one of the most important benefits of this structure for the investor looking for income. Once again, the bond ladder offers great opportunities to the committed municipal bond investor.

Detroit and other discontents

Detroit’s seeking protection from its creditors via a Chapter 9 bankruptcy filing was probably the biggest headline news of the year. We were not especially surprised to see this happen, but what was surprising was Detroit’s emergency manager’s declaration that general obligation debt holders had no priority on claims. In essence, such debt holders were told to get in the same line for payment with everyone from city employees to the City Hall coffee vendor.

If this stands, it would violate all understandings of how general obligation debt is prioritized in a bankruptcy filing. Our president, Ronald P. Bernardi, wrote an extensive piece on this on December 20th that is well worth reviewing again. Among the points he makes is that some national precedents could be set by the eventual rulings of the U.S. Bankruptcy Court overseeing Detroit’s filing.

Investors have speculated on which other issuers may experience similar distress. An August 26th front-page Barron’s article detailed the weak credit profile of the commonwealth of Puerto Rico, leading to a significant selloff of its debt. The pension funding woes of the state of Illinois also have come under increasing scrutiny. These problems have not only put pressure on Puerto Rico and Illinois state issues, but have weighed on the municipal market overall.

On the other hand, this has reinforced the importance of another key part of the Bernardi process – a rigorous attention to credit quality. Our managed accounts have never invested in Detroit, and we have steered clear of Illinois state debt and Puerto Rico issues for several years. Paying close attention to the three pillars of credit research – deal purpose, deal structure, and underlying credit quality – has enabled our clients to avoid both widely publicized credit issues and others less famous, but no less severe.

Bernardi’s credit research team also offers opportunities as well as protection for our investors. As noted, we have avoided Illinois state debt for some time; however, there are many well-run municipalities in Illinois whose debt trades at higher levels due solely to being located in this state. Our knowledge of such municipalities allows us to invest in this debt and capture these higher rates for our clients, while maintaining a vigilant eye on their ongoing finances to make sure that both interest payments and principal are protected. We consider our clients’ portfolios as their “mattress money,” and always act with that in mind.

Moving on, and benefitting, from 2013

2013 was a challenging year for the fixed income market, both taxable and tax-exempt. The upwards shift in the yield curve, large and continuing withdrawals from municipal bond funds and ETFs, and the headlines coming out of Detroit and other pressured issuers can leave the investor justifiably wondering if the municipal bond market is indeed in dangerous territory (or wēi). Particularly when looking at the increase in intermediate and long-term rates during the year, the issue of whether we are at a crucial or critical turning point (or jī) for the market can be vigorously debated.

On the other hand, the Bernardi commitment to separate account, laddered portfolios offers an opportunity to those committed to seeking income, and especially tax-exempt income. Almost all of our portfolios handled the decline in the municipal market better than the primary Barclays index or the average mutual fund or ETF. The laddering structure means that our clients have bonds that will soon mature and can be reinvested at new, higher yields. Finally, our credit research process helps our investors avoid pitfalls like Detroit, while finding quality issuers offering above-market yields.

Bernardi Securities is now entering its 30th year of turning potential “danger” into “opportunity” for our clients. We remain committed to doing so for the benefit of our clients in the years to come.

Thank you for your continued confidence in our bond portfolio research and management process. Please always feel free to contact us if you have any questions, or would like us to review your portfolio with you.

Scott R. Rausch, CFA
Portfolio Manager
January 22, 2014


By Ronald P. Bernardi


Will the Detroit Chapter 9 bankruptcy turn the municipal bond world upside down? A random vacation photo captured this concern fairly well. With such a big question looming over the market, let’s review the ways in which the largest municipal bankruptcy in our nation’s history may set precedents for municipalities across the country.

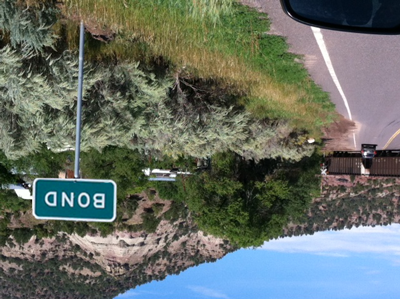
The vacation photo worth 1700 words

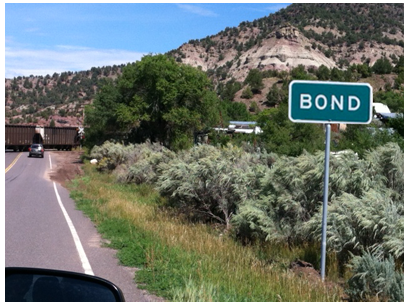
Bond, Colorado sits at 6600 feet in the northwestern part of the state approximately 135 miles west of Denver. The Colorado River cuts through the town that is home to 183 hardy people. The summers are cool, mild, dry and short; the winters are long and cold. It is both a beautiful and desolate place.

State Highway 131 runs north to south snaking along portions of the meandering Colorado River. A Union Pacific rail line runs parallel to State Highway 131 before taking a hard turn crossing it in Bond.

This past September I spent some unscheduled time in Bond, forced to stop at the intersection of Highway 131 and the Union Pacific rail line. A combination of flashing red crossing signals (there were no gates) and a rumbling, seemingly endless freight train pulling a lot of Colorado coal allowed me to take in Bond for about 10 minutes.

Instead of passing the time counting freight cars I took in the vast landscape, the nearby Colorado and noticed a photo opportunity. I asked my trusted co-pilot of these last 29 years, my wife Beth, to lean out the window and take a photograph.

Beth snapped the photo and forwarded it to me electronically. It arrived on my desktop in an inverted state and I knew immediately I could use it somehow. Today, the photo makes its illustrative debut.

Detroit, Michigan lies 1400 miles to the east of Bond. What transpires in Motor City in the coming months may very well turn the municipal bond world upside down.

Full faith and credit pledge questioned

Earlier this month U. S. Bankruptcy Judge Steven Rhodes ruled that Detroit is eligible to enter into Chapter 9 bankruptcy and pension benefits are not entitled to any heightened protection in municipal bankruptcy. His ruling means the city of Detroit government’s workers and retirees cannot count on state constitution guarantees to protect pension benefits. Practically speaking, the ruling serves as an invitation for creditors to reach a settlement with the city and hopefully will lead to meaningful out of court negotiations on pension reform. His ruling came in spite of vigorous objections filed by union and retirees’ lawyers. Bond investors and bond insurers did not object to the city’s bankruptcy filing.

Judge Rhodes’s 143 page “Opinion Regarding Eligibility” serves as a Chapter 9 tutorial. It provides a painstakingly thorough summary of how Detroit arrived at its current disastrous state and his rationale for granting the city’s request to file. We do not envy the position Judge Rhodes finds himself in the middle of for this is only the beginning of what will prove to be a long, bruising battle of a very complicated situation. A union and multiple pension systems have filed an appeal of the ruling. To borrow from John Paul Jones, the father of the U.S. Navy, the various class of creditors “have just begun to fight!”

Many of Detroit’s creditors will attempt to advance the notion that their interests are superior to all others. Judge Rhodes will have to parse through all of the legal nuances and details before approving an equitable exit plan for Detroit and its many creditors. The bottom line is obvious — there simply are insufficient funds to honor all unsecured obligations and therefore, most creditors will be forced to take less than what they are owed.

That said, certain debt obligations are legally superior because they are secured by a lien on a specific revenue stream. Debt obligations secured by a revenue stream with adequate current cash flow to cover the debt must be honored. Detroit has outstanding debt obligations that fall into this category and these bonds should not be diminished as part of Chapter 9 unless creditors agree to do so.

Detroit also has other outstanding debt obligations where determining payment priority may be problematical for Judge Rhodes if the city maintains its current position. Certain creditors stand on firmer ground than others regarding these claims, in our view. It is imperative any workout plan advanced by the city and approved by Judge Rhodes recognize that within this group, certain debt obligations are superior to other debts. Specifically, I am referring to Detroit’s voter approved unlimited tax general obligation bonds (UTGO) and limited tax general obligation bonds (LTGO).

Earlier this year, Detroit’s emergency manager proclaimed these debt obligations are “unsecured” and therefore would be treated similarly to all other “unsecured ” debts. His position is that voter approved UTGO and LTGO bondholders should take the same haircut as all other unsecured creditors and receive pennies on the dollar. This is a shortsighted and incorrect position, in our view.

If the city’s position on this issue remains unchanged, a key question should be addressed by Judge Rhodes as part of Detroit’s reorganization — how should general obligation debt be treated relative to other debt obligations, secured and unsecured?

Firstly, we want to make very clear that Bernardi Securities, Inc. has not traded Detroit debt for decades. Detroit has been an unfit credit for conservative bond portfolios for many years. Therefore, it has never qualified for the Bernardi Securities approved list of credits. We have no axe to grind related to Detroit, MI debt.

That said, what does “full faith and credit” mean? Are voter approved unlimited tax general obligation bonds “unsecured”?

“The Series 2005-B Bonds are being issued for the purpose of financing the cost of certain capital projects of the City and paying costs of issuance associated with the Series 2005-B Bonds…The Bonds are full faith and credit unlimited tax general obligations of the City duly authorized by the City’s voters and secured by a pledge of the full faith and credit of the City. The City is authorized and required to by law to levy and collect ad valorem taxes without limitation as to rate or amount upon all taxable property in the City to pay the principal of and interest on the Bonds when due.”

The affirmations above are taken directly from the final official statement of the City of Detroit, Michigan Series 2005-B bond issue. Yet, the city’s emergency manager claims the issue is “unsecured”.

Years ago, voters approved a tax increase to specifically fund the issue’s debt service. Investors relied on tax levy segregation and the above security interest language in deciding to lend money to the city. Today, these taxes are being collected in sufficient amount to pay principal and interest on this bond issue. Yet, the city has decided to divert these taxes for general fund purposes.

Clarity needed on Detroit’s debt issues

The city’s misallocation of these funds raises issues and questions that Judge Rhodes will have to address in order for Detroit to cleanly emerge from bankruptcy. The judge’s ruling is clear that the final debt adjustment plan must treat similar creditors equally. To us, an investor in a voter approved unlimited tax general obligation bond issue is not in the same credit line as a limited tax general obligation bond holder, a certificate of participation debt holder, a note holder or the coffee vendor provided the tax collections are sufficient to cover interest and principal payments. This seems fairly obvious to us.

Perhaps, Mr. Orr will change his tactics toward bondholders given this month’s ruling and what it means for potential reduction of pension liabilities. If not, Judge Rhodes needs to exercise a degree of judicial discretion applying principles of equity in order to fashion an exit plan for the city. Emergency manager Orr’s one-size-fits-all debt holder plan is inappropriate.

Clarity is needed from the judge on numerous issues related to debt issues:

  • Secured vs. unsecured debt. Clarity as to which debt is “secured” and which debt is “unsecured”; what do those terms mean?
  • Legality of unauthorized tax collection. Clarity as to whether the voter approved unlimited ad valorem tax putatively securing Series 2005-B bonds (and other similar tax levies) can be legally assessed and collected if used for purposes other than what the voters authorized. Doesn’t the city’s misallocation of these funds make the tax invalid? If not, why bother holding an election?
  • Legality of tax revenue diversion. Clarity as to whether revenue from tax millage collection can legally be diverted from LTGO bond payments to cover the city’s operating expenses. Does the state constitution, in fact, allow for the diversion of these revenues?
  • Legality of Orr’s casino revenue/DIP plan. Clarity as to whether Mr. Orr’s plan to use casino revenues to secure Detroit’s proposed debtor-in-possession financing (DIP) is legal. Is granting a super-priority status to new DIP lenders equitable to general obligation bondholders if they are forced to accept Mr. Orr’s pennies on the dollar offer?

A sensible solution may be to implement a distribution waterfall structure for “unsecured” debt holders, similar to how private equity operates. Establishing a hierarchy delineating the order and priority in which funds will be distributed to various classes of debt holders will ensure that different types of investors have priority of payment compared to others.

There is a great deal for Detroit riding on its workout plan. If it does not treat UTGO and LTGO bondholders equitably it will increase its future borrowing costs. Additionally, the plan’s final details will have important repercussions for debt issues throughout Michigan. This is especially true for UTGO and LTGO bond issues for communities and school districts around the state. Perhaps, the state government will enter into the discussion now that Judge Rhodes has ruled on the filing issue. Lastly, to a lesser extent some national precedents will be established by Detroit’s court approved Chapter 9 exit plan.

It will be interesting to watch this one develop and see if Detroit turns the bond world upside down.

Ronald P. Bernardi
President and CEO
Bernardi Securities, Inc.
December 20, 2013